


Combining GEAR with WEF: the benefits of diversification
When building portfolios, investors face not only the problem of selecting the right investments, but also that of combining them in the right way. Do the Jupiter Merian Global Equity Absolute Return Fund (GEAR) and the Jupiter Merian World Equity Fund (WEF) overlap?
The two funds are managed by the same team and have the same core investment engine, but their return streams are very different because they are constructed quite differently. GEAR is a market-neutral fund. It holds a long and a short book in balance. It does not express a directional view on the market. GEAR’s returns come from alpha, not market beta. WEF, by contrast, is a long-only global equity fund. It has only a long book and its correlation with global equity markets is high. Returns come from a combination of market beta and alpha.
Both GEAR and WEF have enjoyed strong performance in recent years. GEAR (I USD Acc) returned 14.0 percent over one year, 43.2 percent over three years, and 72.9 percent over five years, as at 30 September 2026. WEF (I USD Acc) returned 19.1 percent over one year, 94.9 percent over three years, and 93.8 percent over five years, as at 30 September 2026.
Diversification benefits
The analysis below shows that combining GEAR and WEF has provided diversification benefits over the past decade.
We constructed three hypothetical portfolios, combining different weights of the two funds and the Bloomberg Global Aggregate Index, an index of global investment-grade bonds, hedged into USD (shown as “Bonds” below).
Portfolio 1: 60 percent WEF, 40 percent Bonds, 0percent GEAR
Portfolio 2: 60 percent WEF, 20 percent Bonds, 20percent GEAR
Portfolio 3: 60 percent WEF, 0 percent Bonds, 40percent GEAR
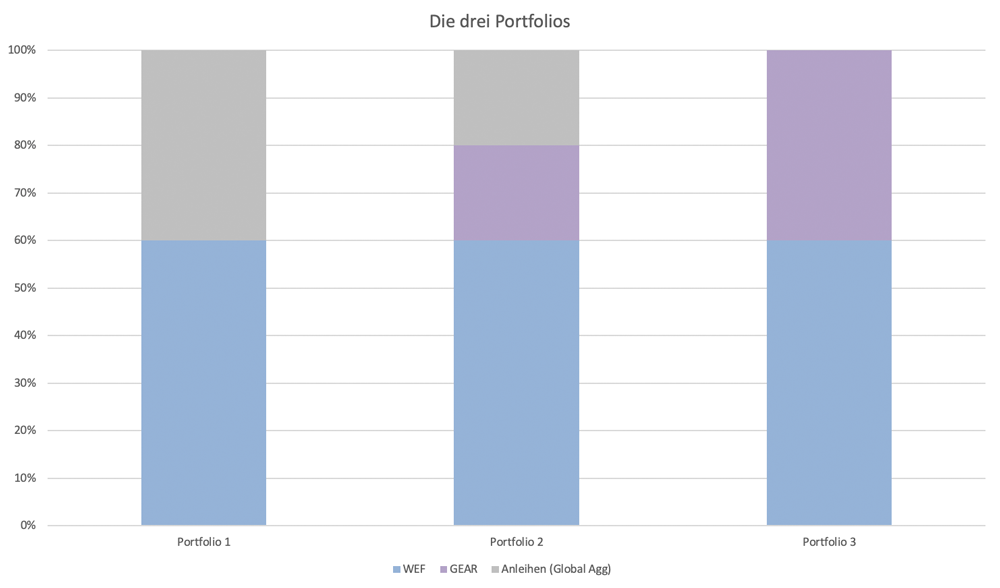
Source: Jupiter. For illustrative purposes only.
Summary statistics for the underlying constituents and the three portfolios over the 10-year period to 30 September 2026 are shown in the table below.
|
WEF (I USD Acc) |
GEAR (I USD Acc) |
Anleihen (Global Agg) |
MSCI World NR |
Portfolio 1 |
Portfolio 2 |
Portfolio 3 |
|
|
Annualised return |
13.97 percent |
6.73 percent |
1.61 percent |
12.81 percent |
9.13 percent |
10.25 percent |
11.37 percent |
|
Annualised volatility |
15.18 percent |
5.12 percent |
4.01 percent |
14.81 percent |
9.89 percent |
9.51 percent |
9.31 percent |
|
Sharpe ratio |
0.75 |
0.82 |
−0.22 |
0.69 |
0.67 |
0.81 |
0.95 |
Source: Morningstar, Jupiter, 30 September 2026. 10 years, USD. Funds net of fees; index gross of fees. Portfolios rebalanced to target weights monthly, with no transaction costs assumed. USTREAS Federal Funds annualised return 2.5 percent. Portfolios are hypothetical. Past performance does not predict future returns.
Over this ten year period and over these market conditions, Portfolio 3 (60 percent WEF, 40 percent GEAR) provided both the highest return and the lowest volatility of the three portfolios. It also achieved a Sharpe ratio higher than either fund on its own. This is a textbook sign of achieving the benefits of diversification by combining two assets that are very different from each other. GEAR’s monthly correlation with WEF over the 10 years shown was about zero.
While bonds did provide some diversification from equities, they provided less than GEAR during this period.
The frontier analysis below shows that over this historical 10-year period holding 20 percent or 40 percent in GEAR shifted the WEF/Bonds line (of the realised risk-return frontier) upwards and to the left (higher return with lower volatility).
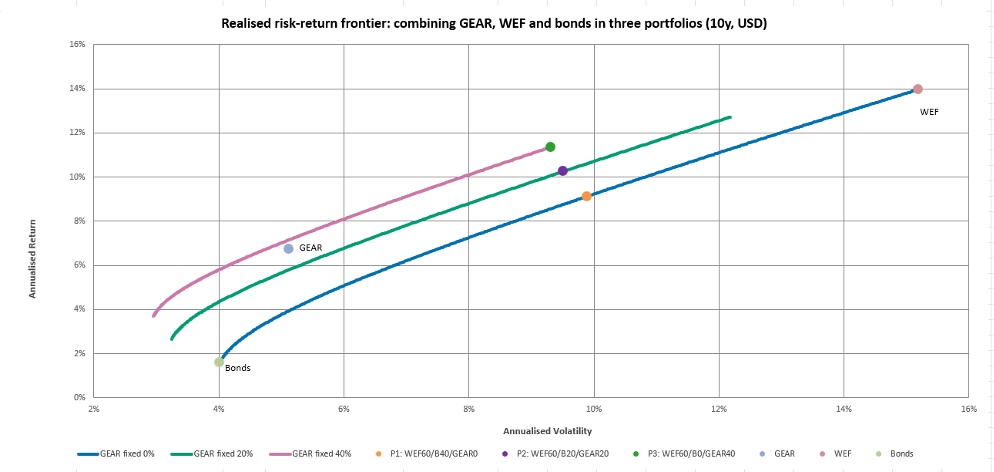
Source: Morningstar, Jupiter, 30 September 2026. 10 years, USD. Funds net of fees; index gross of fees. Portfolios rebalanced to target weights monthly, with no transaction costs assumed. Portfolios are hypothetical. Past performance does not predict future returns.
Seeking diversification from equities
Fixed income has traditionally been relied on for diversification from equities, although that role has come into question because the correlation between equities and bonds is not stable. According to Ibbotson, the 10-year correlation between US stock and bond returns has varied substantially over time and has often been positive.1 For much of the 1980s, the correlation was around +0.3 or +0.4 (correlation is measured between −1.0 and +1.0). Around the turn of the century, it fell sharply and became negative, remaining so for much of the 2000s and 2010s, only to rise rapidly and become positive by the end of 2023. The analysis above suggests that combining GEAR and WEF in a portfolio provided good diversification benefits over this period, superior to combining WEF with bonds.
1 Roger G. Ibbotson, “Exponential Wealth: Centuries of Stock and Bond Returns”, CFA Institute Research Foundation, 2026, page 180, Exhibit 10.4.
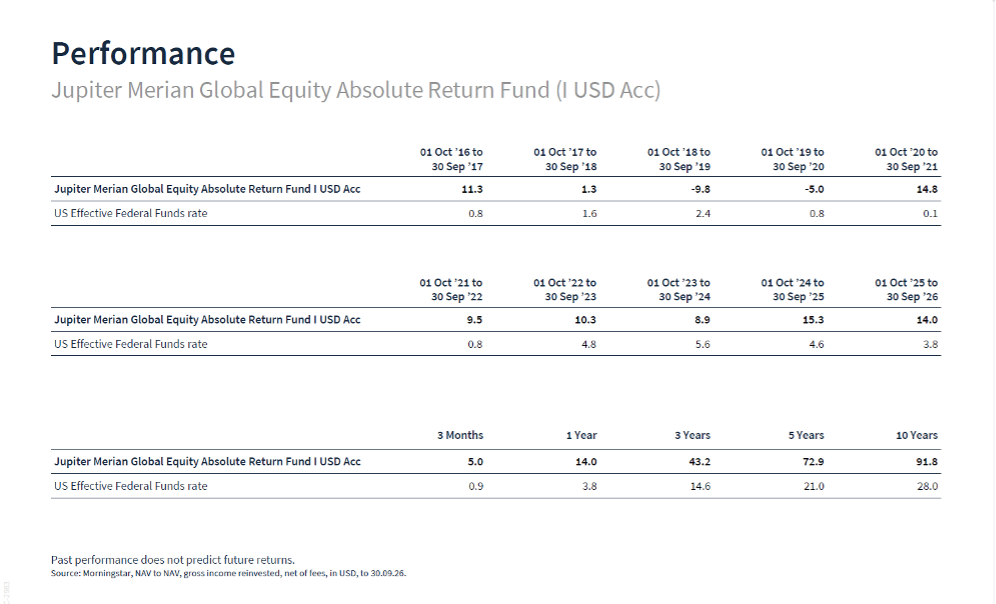
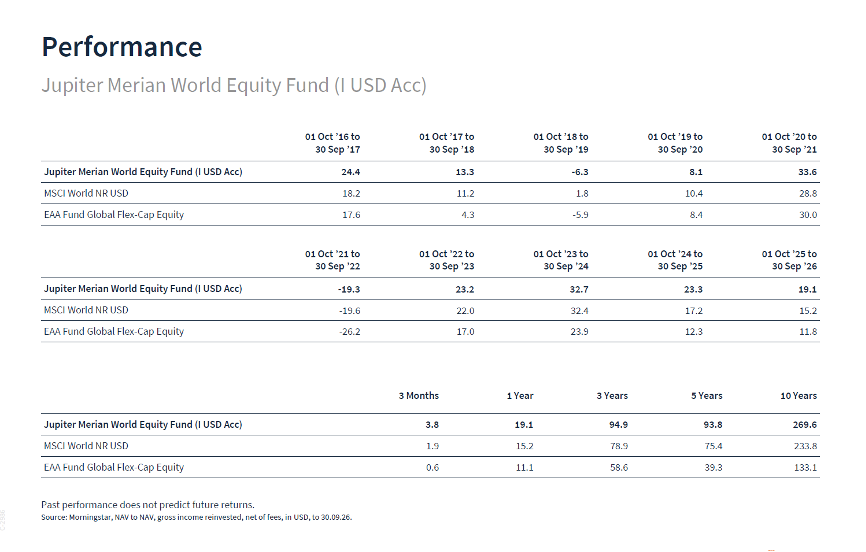
Jupiter Merian Global Equity Absolute Return Fund
Fund Risks
Pricing risk - Price movements in financial assets mean the value of assets can fall as well as rise, with this risk typically amplified in more volatile market conditions.
Derivative risk - the Fund may use derivatives to generate returns and/or to reduce costs and the overall risk of the Fund. Using derivatives can involve a higher level of risk. A small movement in the price of an underlying investment may result in a disproportionately large movement in the price of the derivative investment.
Counterparty Default Risk - The risk of losses due to the default of a counterparty on a derivatives contract or a custodian that is safeguarding the fund’s assets.
ESG - Investments are selected or excluded on both financial and nonfinancial criteria. The Fund’s performance may differ from the broader market or other Funds that do not utilise ESG criteria when selecting investments.
Charges from capital - Some or all of the Fund’s charges are taken from capital. Should there not be sufficient capital growth in the Fund this may cause capital erosion.
Stock Connect risk - Stock Connect is governed by regulations which are subject to change. Trading limitations and restrictions on foreign ownership may constrain the Fund’s ability to pursue its investment strategy.
ESG Data - The Fund uses data from third parties (which may include providers for research, reports, screenings, ratings and/or analysis such as index providers and consultants) and that information or data may be incomplete, inaccurate or inconsistent.
For a more detailed explanation of risks, please refer to the “Risk Factors” section of the prospectus.
Jupiter Merian World Equity Fund
Fund Risks
Currency (FX) Risk - The Fund can be exposed to different currencies and movements in foreign exchange rates can cause the value of investments to fall as well as rise.
Pricing risk - Price movements in financial assets mean the value of assets can fall as well as rise, with this risk typically amplified in more volatile market conditions.
Market Concentration Risk (Geographical Region/Country) - Investing in a particular country or geographic region can cause the value of this investment to rise or fall more relative to investments whose focus is spread more globally in nature.
Derivative risk - the Fund may use derivatives to reduce costs and/or the overall risk of the Fund (this is also known as Efficient Portfolio Management or “EPM”). Derivatives involve a level of risk, however, for EPM they should not increase the overall riskiness of the Fund.
Counterparty Default Risk - The risk of losses due to the default of a counterparty on a derivatives contract or a custodian that is safeguarding the fund’s assets.
ESG - Investments are selected or excluded on both financial and nonfinancial criteria. The Fund’s performance may differ from the broader market or other Funds that do not utilise ESG criteria when selecting investments.
ESG Data - The Fund uses data from third parties (which may include providers for research, reports, screenings, ratings and/or analysis such as index providers and consultants) and that information or data may be incomplete, inaccurate or inconsistent.
For a more detailed explanation of risks, please refer to the “Risk Factors” section of the prospectus.
Important information
Marketing communication. This document is intended for investment professionals and is not for the use or benefit of other persons, including retail investors. The value of investments and income may go down as well as up and investors may not get back amounts originally invested. Exchange rate changes may cause the value of investments to fall as well as rise. Every effort is made to ensure the accuracy of any information provided but no assurances or warranties are given. An investment constitutes the acquisition of shares in the sub-fund, not in the sub-fund’s underlying assets. This document is for informational purposes only and is not investment advice. This is not an invitation to subscribe for shares in the Jupiter Asset Management Series plc (the Company) or any other fund managed by Jupiter Asset Management (Europe) Limited or Jupiter Asset Management Limited. The Company is an investment company with variable capital established as an umbrella fund with segregated liability between sub-funds which is authorised and regulated by the Central Bank of Ireland pursuant to the European Communities (Undertakings for Collective Investment in Transferable Securities) Regulations 2011, as amended. Registered in Ireland under registration number 271517. Registered office: 33 Sir John Rogerson’s Quay, Dublin 2, Ireland. Please refer to the latest Prospectus and to the Key Investor Information Document (KIID) (for investors based in the UK) and Key Information Document (KID) (for investors based in the EU) before making any investment decision. Particularly to the sub-fund’s investment objective, characteristics including those related to ESG (if applicable), and additional risk factors. These documents are available from www.jupiteram.com or from www.eifs.lu/jupiteram or from: France: BNP Paribas Securities Services, Les Grands Moulins de Pantin, 9 rue du Debarcadère 93500 Pantin, France. Hong Kong: Jupiter Asset Management (Hong Kong) Limited, Unit 1501, Level 15, AIA Central, 1 Connaught Road Central, Central, Hong Kong. Italy: Allfunds Bank S.A.U., Milan Branch, Via Bocchetto, 6, 20123 Milano, Italia; Societe Generale Securities Services S.p.A, Via Benigno Crespi 19A – MAC2, Milan. The sub-fund has been registered with the Commissione Nazionale per le Società e la Borsa (CONSOB) for the offer in Italy to retail investors. Singapore: Jupiter Asset Management (Asia) Private Limited, 10 Collyer Quay #40-00 Ocean Financial Centre, Singapore 049315. Spain: Allfunds Bank, C/ La Estafeta 6, Edificio 3, 28109 Alcobendas, Madrid, Spain. For the purposes of distribution in Spain, the Company is registered with the Spanish Securities Markets Commission – Comisión Nacional del Mercado de Valores (“CNMV”) under registration number 301, where complete information, including a copy of the marketing memorandum, is available from the Company authorised distributors. Subscriptions should be made through a locally authorised distributor. The net asset value is available on www.jupiteram.com. Switzerland: Copies of the Memorandum and Articles of Association, the Prospectus, KIIDs and the annual and semi-annual reports of the Company may be obtained free of charge from the Company’s representative and paying agent in Switzerland, NPB Neue Privat Bank AG Limmatquai 1 | am Bellevue Postfach CH-8024 Zürich, and First Independent Fund Services Limited, Klausstrasse 33, CH-8008 Zurich, Switzerland. Taiwan: Capital Gateway Securities Investment Consulting Enterprise, 9F/9F-1, No. 171, Songde Road, Xinyi District, Taipei City, Taiwan, R.O.C. United Kingdom: Jupiter Asset Management Limited (the Investment Manager and UK Facilities Agent), registered address: The Zig Zag Building, 70 Victoria Street, London, SW1E 6SQ, United Kingdom, authorised and regulated by the Financial Conduct Authority. Information is also available on how subscriptions and redemptions can be made, and arrangements related to investor rights and complaints handling. Unless otherwise specified in this document, The Bank of New York Mellon SA/NV, Dublin Branch / BNY Mellon Fund Services (Ireland) Designated Activity Company (the Company’s Depositary and Administrator respectively) is responsible for processing subscription, repurchase and redemption orders and making other payments to Shareholders. Depositary and Administrator address: The Shipping Office, 20-26 Sir John Rogerson’s Quay, Dublin 2, D02 Y049. Ireland, email Distributors:


