


Jupiter European Select: A Year Of Progress In Equities Investing
By Paolo Schiavano, Sales Director Switzerland
It is an exciting period for European equity investors. Returns through mid-August have been healthy, perhaps reflecting that Europe is one of the few developed markets offering opportunity for genuine diversification at a time when global investors are increasingly aware of concentration risk in US and technology holdings.
For Jupiter, this backdrop coincides with an important milestone. Just over a year ago, Niall Gallagher and his co-investment managers, Chris Legg and Christopher Sellers, joined the company, bringing with them a long-established partnership and an investment process tested across multiple market cycles.
Flexible approach
The team manages a concentrated, high-conviction portfolio through a bottom-up, research-intensive and style-agnostic approach. They focus on companies that can sustainably generate returns on capital employed above their cost of capital – or have a credible path to doing so – and whose management teams allocate capital intelligently.
Over the past year, the team has added another period of relative outperformance to its longer-term track record, while taking advantage of several investment themes across Europe. Encouragingly, investor interest has followed: Jupiter’s July earnings report cited the European equities strategy among those attracting positive fund flows.
Risk-focused portfolio
Careful portfolio construction is a critical part of the process. The team seeks to concentrate risk in stock selection while minimising factor biases, resulting in a focused portfolio of 30-50 companies spanning a wide range of structural growth trends and idiosyncratic opportunities.
Jupiter European Select is currently overweight banks, industrials and electrification names, while underweight healthcare. Banks are an example of where the team saw an inflection of returns. The team added exposure to selected banks, recognising an improvement in the sector’s profitability that it believes is still not fully reflected in valuations. Recent results have reinforced that view, with many banks continuing to “beat and raise” expectations or deliver against forecasts that had already been upgraded. Strong net interest income, emerging loan growth, robust fee income, contained costs and low credit losses have supported profitability.
Yet earnings strength has not been confined to financials. The second-quarter reporting season was healthy across much of the European market. The Stoxx 600 index is on track for the strongest year-on-year earnings growth since 20221, and many of the structural trends represented in the portfolio remain positive.
Diversification opportunity
European equities currently trade closer to long-term average valuations and at a discount to the US2. Market concentration also is considerably lower: the top 10 companies represent around 15 percent of the main European index versus 43 percent in the US3. Meanwhile, less than half of listed European companies’ revenues are generated domestically, providing exposure to globally competitive businesses and reducing dependence on any single European economic outcome.
There is also a striking difference in technology exposure. Broadly defined, technology and the “AI trade” represent around 12-15% of European equities, including electrical industrial companies, well below North American, Asian and emerging-market indices.4
We believe there are compelling structural themes to invest behind in Europe, and that market dislocation may continue to benefit active managers that are thoughtfully positioned. We also believe European equities remain an environment where a patient, flexible, research-driven approach may add real and lasting value.
Fund performance
Jupiter European Select Sicav
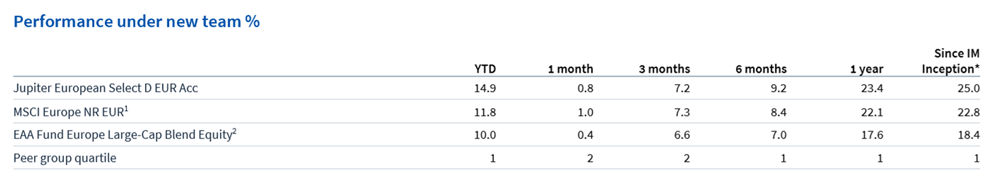
Past performance does not predict future returns. Source: Morningstar, NAV to NAV, gross income reinvested, net of fees, Jupiter European Select D EUR Acc, to 31.07.26. 1Benchmark: MSCI Europe NR EUR. With effect from 9 December 2025, the fund’s comparator benchmark changed from the FTSE World Europe Index to the MSCI Europe Net Total Return Index. Historical benchmark performance shown uses the current comparator benchmark. 2Peer group: EAA Fund Europe Large-Cap Blend Equity. * Since IM Inception 12.05.25.
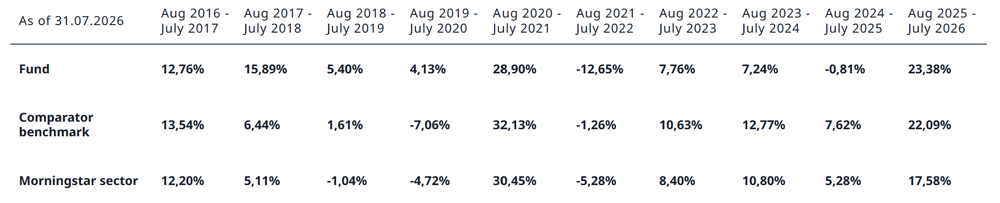
Past performance is no indication of current or future performance. Performance data does not take into account commissions and costs incurred on the issue and redemption of shares. Source: Morningstar, Jupiter Asset Management Limited. Share price stated close to close and includes any reinvestment income. NAV per Ordinary Share is the cumulative income NAV with debt at fair value and includes any reinvested income.
Fund risks
Currency (FX) Risk - The Fund can be exposed to different currencies and movements in foreign exchange rates can cause the value of investments to fall as well as rise.
Pricing Risk - Price movements in financial assets mean the value of assets can fall as well as rise, with this risk typically amplified in more volatile market conditions.
Market Concentration Risk (Geographical Region/Country) - Investing in a particular country or geographic region can cause the value of this investment to rise or fall more relative to investments whose focus is spread more globally in nature.
Derivative risk - the Fund may use derivatives to reduce costs and/or the overall risk of the Fund (this is also known as Efficient Portfolio Management or "EPM"). Derivatives involve a level of risk, however, for EPM they should not increase the overall riskiness of the Fund.
Counterparty Default Risk - The risk of losses due to the default of a counterparty on a derivatives contract or a custodian that is safeguarding the Fund's assets.
ESG - Investments are selected or excluded on both financial and non-financial criteria. The fund's performance may differ from the broader market or other funds that do not utilise ESG criteria when selecting investments.
ESG data - The fund uses data from third parties (which may include providers for research, reports, screenings, ratings and/or analysis such as index providers and consultants) and that information or data may be incomplete, inaccurate or inconsistent. For a more detailed explanation of risk factors, please refer to the "Risk Factors" section of the KIDs (Key Information Documents).
- More information about Jupiter Asset Management here
Sources:
1 Financial Times, 9.8.26. Investors return to European stocks as strong earnings lift Iran war gloom.
2 FactSet, Goldman Sachs Global Investment Research, as at 4.26. MSCI US 21.5x, Stoxx 600 14.7x
3 Jupiter, Factset as at 30.4.26. Refers to S&P 500 for US, Stoxx 600 for Europe.
4 Jupiter, Bloomberg as at 30.4.26. Refers to MSCI North America, Taiwan, Korea, EM indices.
Important information
This is a marketing communication. This document is intended for investment professionals and is not for the use or benefit of other persons, including retail investors. This document is for informational purposes only and is not investment advice. The value of investments and income may go down as well as up and investors may not get back amounts originally invested. Exchange rate changes may cause the value of investments to fall as well as rise. Past performance does not predict future returns. The views expressed are those of the individuals mentioned at the time of writing, are not necessarily those of Jupiter as a whole, and may be subject to change. This is particularly true during periods of rapidly changing market circumstances. Company or holding examples are for illustrative purposes only and are not a recommendation to buy or sell. Every effort is made to ensure the accuracy of the information, but no assurance or warranties are given. The Company is a UCITS fund incorporated as a Société Anonyme in Luxembourg and organised as a Société d’Investissement à Capital Variable (SICAV). Please refer to the latest Prospectus and to the Key Investor Information Document (KIID) (for investors based in the UK) and Key Information Document (KID) (for investors based in the EU) before making any investment decision. Particularly to the sub-fund’s investment objective, characteristics including those related to ESG (if applicable), and additional risk factors. These documents are available from www.jupiteram.com or from www.eifs.lu/jupiteram or from: France: CACEIS Bank France (Centralising Agent), 1/3 Place Valhubert, 75013 Paris, France. Italy: Allfunds Bank, S.A.U., Milan Branch, Via Bocchetto 6, 20123 Milano, Italy. CACEIS Bank, Italy Branch Via Piazza Cavour 2,20121 Milano, Italy. Société Générale Securities Services, Via Benigno Crespi 19, 20159 Milano, Italy. The sub-fund has been registered with the Commissione Nazionale per le Società e la Borsa (CONSOB) for the offer in Italy to retail investors. Luxembourg: the Company’s registered office: 31 Z.A. Bourmicht L-8070 Bertrange, Grand Duchy of Luxembourg. Spain: Allfunds Bank, C/ La Estafeta 6, Edificio 3, 28109 Alcobendas, Madrid, Spain. For the purposes of distribution in Spain, the Company is registered with the Spanish Securities Markets Commission – Comisión Nacional del Mercado de Valores (“CNMV”) under registration number 1253, where complete information, including a copy of the marketing memorandum, is available from the Company authorised distributors. Subscriptions should be made through a locally authorised distributor. The net asset value is available on www.jupiteram.com. Hong Kong: Jupiter Asset Management (Hong Kong) Limited, Unit 1501, Level 15, AIA Central, 1 Connaught Road Central, Central, Hong Kong . Switzerland: The representative in Switzerland is FIRST INDEPENDENT FUND SERVICES LTD., Feldeggstrasse 12, CH-8008 Zurich. The paying agent in Switzerland is NPB New Private Bank Ltd., Limmatquai 1, CH-8001 Zurich. The prospectus, the key information documents, the articles of association as well as the annual and semi-annual reports may be obtained free of charge from the representative in Switzerland. United Kingdom: Jupiter Asset Management Limited (the Investment Manager and UK Facilities Agent), registered address: The Zig Zag Building, 70 Victoria Street, London, SW1E 6SQ, United Kingdom, authorised and regulated by the Financial Conduct Authority. Information is also available on how subscriptions and redemptions can be made, and arrangements related to investor rights and complaints handling. Unless otherwise specified in this document, The Bank of New York Mellon SA/NV, Luxembourg Branch (the Company’s Depositary and Administrator) is responsible for processing subscription, repurchase and redemption orders and making other payments to Shareholders. The Bank of New York Mellon SA/NV, Luxembourg Branch, Luxembourg Branch,2-4,Rue Eugène Ruppert, L-2453 Luxembourg, email Distributors:


